Parsing the New Life Insurance C-1 RBC Charges for CLOs/CBOs/CDOs
This summer was anything but dull for life insurers and their investment directors.
Key Takeaways
- The NAIC approved a new set of risk-based capital charges for CLOs, CBOs and CDOs held by life insurers. They go into effect December 31, 2026.
- For securities rated 1F (A2) and above, the new charges will be dramatically lower. For those rated 1G (A2) and below, charges will be significantly higher.
- Given the changes, we expect life insurers to shift their allocations.
- We could see increased offerings of CBOs and CDOs, that have top tranches at 1F (A2) or higher.
After a four-year review process, the National Association of Insurance Commissioners (NAIC) approved new C-1 Risk Based Capital (RBC) charges for the following securities held by life insurers:
- Collateralized Loan Obligations (CLOs)
- Collateralized Bond Obligations (CBOs)
- Collateralized Debt Obligations (CDOs)
While the topic may not be the spiciest for a broad audience, it is a hot topic in life insurance circles. We believe tens of millions of dollars may be reallocated in the CLO/CBO/CDO space amid an increase in offerings in certain ratings tiers. Read on for the details.
Barring a delay, the new C-1 charges for CLOs/CBOs/CDOs will go into effect December 31, 2026.1 The changes are best thought of in three parts, which are described below and displayed in the following tables.
NAIC Changes in Three Parts
PART ONE
For CLO/CBO/CDO securities rated NAIC 2B (Baa2) or higher, the factors shown in the table below apply without adjustment for broadly syndicated loan (BSL) CLO tranche thickness.2

Source: US NAIC, as of July 23, 2026.
PART TWO
For CLO/CBO/CDO securities rated NAIC 2C (Baa3) or lower, the factors on the left side of the table below apply to BSL CLOs with tranche thicknesses of 4% or greater.

Source: US NAIC, as of July 23, 2026.
PART THREE
For BSL CLO securities rated NAIC 2C (Baa3) or lower, the factors on the right side of the table below apply to tranche thicknesses below 4%.

Source: US NAIC, as of July 23, 2026.
Ratings the Key Determinant
C-1 RBC charges for CLOs/CBOs/CDOs rated 1F (A2) and above, were dramatically lowered to a range of only 9% to 26% of prior charge levels. Looking closely at the charge differential between 1A (AAA) and 1F (A2), it dropped from 66 basis points (bps) to 13 bps.3
Conversely, the NAIC significantly raised charges related to CLOs/CBOs/CDOs rated 1G (A2) and below to a range of 143% to 854% of their former levels. Additionally, life insurers will likely be sensitive to a new decided cliff in C-1 between the 1F to 1G notch crossover.
What Do CLO Exposures Tell Us About Potential Life Insurance Allocations?
As of year-end 2024, the US insurance industry general accounts held $276 billion in CLOs, which fell into the following broad rating buckets:
US Insurance Industry General Account CLO Holdings
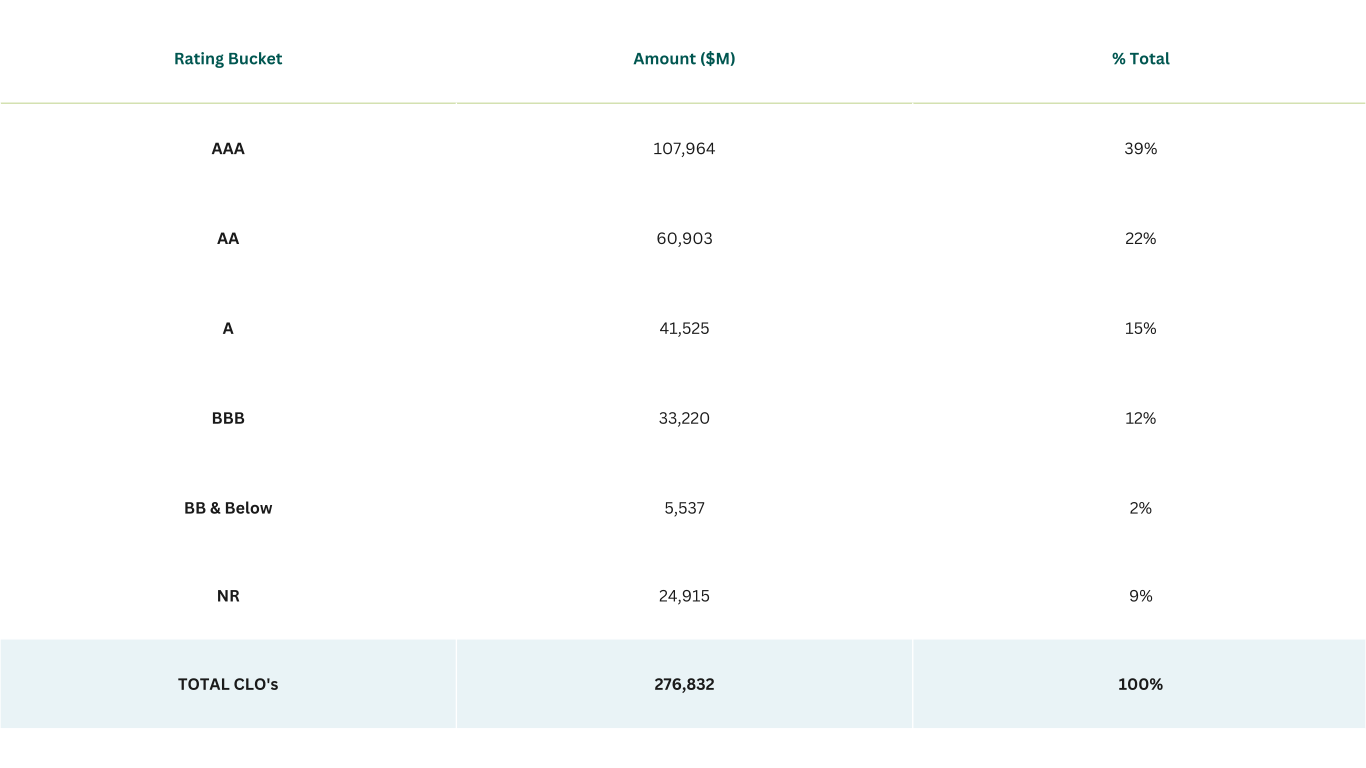
Source: NAIC Capital Markets Special Report, as of December 31, 2024. NR stands for not-rated issues. Does not sum to 100% due to rounding.
Life insurers held 82% of the $276 billion. Assuming the ratings distribution of life insurers’ assets is similar to that of the broad insurance industry (excluding not-rated issues), we estimate that 17% of life insurers’ CLO holdings were rated BBB or below ($32 billion). Depending on what portion of the A rated bucket is composed of 1G (A3) and NR 1G (A3) or below, that number could be higher by a good amount.
Implications for Life Insurer Assets
With the dramatic increase in C-1 for securities rated 1G (A3) or below, we would expect life insurers to eliminate these holdings in favor of similarly rated securitized or corporate securities. Based on the table above, we estimate life insurers will have at least $32 billion and possibly more than $50 billion in CLOs to potentially reallocate.
The dramatic reduction in the differential between 1A (AAA) to 1F (A3) means that the yield/spread pickup hurdle for life insurers to reallocate from 1A (AAA) to 1F (A2) could be much less to adjust for the increased capital charge. Our expectation is that life insurers will look to increase portfolio spread/yield by shifting away from AAA CLOs/CBOs/CDOs in favor of AA1, AA2, AA3, A1 and A2 rated CLOs/CBOs/CDOs.
Additionally, the dramatic decrease in C-1 for securities rated 1F (A2) and higher means life insurers will likely try to reallocate other spread securities like corporates and securitized issues into CLOs/CDOs/CBOs to reduce the C-1 charges on their assets.
Asset liability management implications will need to be assessed when undertaking these portfolio shifts. However, all else equal, life insurers should prefer CLO/CDO/CBO to similarly rated corporates, asset-backed securities and commercial mortgage-backed securities.
Market Response
Additionally, we think issuers will respond to the RBC changes with more offerings of CBOs and CDOs that have top tranches at 1F (A2) or higher. We have already seen asset managers build CBO/CDO structures with the new C-1 RBC charges in mind.
We believe these offerings/structures could be very desirable relative to other fixed income holdings (depending on the yields they offer) given the large C-1 reductions in those rating buckets. This could cause an expansion of CBO/CDO offerings in the market, in our view. Life insurers will likely need to ensure that portfolio guidelines and investment management agreements address CDO/CBO securities where the documents are currently silent on such investments. Credit investing by life insurers and asset managers will need to expand coverage of CBO/CDO managers and their collateral portfolios.
Future NAIC Projects and Actions
While the current C-1 project was based on BSL CLO data and applies to all CLOs/CBOs/CDOs, we believe it is likely that middle market loan (MML) CLOs will be given attention under a future NAIC project.
Like the tranche thickness variation for BSL CLOs under the newly created structure, MML CLOs differ from BSL CLOs in terms of collateral, liquidity, transparency, credit enhancement and covenants. We believe these differences might suggest a different C-1 charge structure from the new one. In our view, the NAIC may undertake additional initiatives if market developments or life insurer allocation trends raise regulatory concerns in sectors such as commercial real estate CLOs, CBOs and CDOs.
Endnotes
1 C-1 refers to the m1inimum capital insurers are required to hold to cover the risk of certain bond holdings. (The RBC charges or property & casualty and health insurers for CLOs/CBOs/CDOs remain unchanged at this time.)
2 Tranche thickness refers to the percentage of a securitization’s total capital structure represented by a specific tranche. Larger tranches are considered “thicker,” while smaller tranches are considered “thinner.”
3 Prior C-1 RBC differential detail: 1A (AAA) at 16 bps and 1F(A2) at 82 bps. Current C-1 RBC differential detail: 1A at 4 bps and 1F at 17 bps.
Sources
NAIC Capital Markets Special Report, “U.S. Insurers’ Total Collateralized Loan Obligation Investments Pace of Growth Slows in 2024”, Johnson, Carelus, Lee.
Loomis Sayles & Company, “Q1 2026 Insurance Solution Highlights”.
NAIC RBC Investment Risk and Analysis Working Group, New Life RBC Factors for CLOs, CBOs and CDOs, June 23, 2026.
Disclosure
This marketing communication is provided for informational purposes only and should not be construed as investment advice. Investment decisions should consider the individual circumstances of the particular investor. Any opinions or forecasts contained herein, reflect the subjective judgments and assumptions of the authors only, and do not necessarily reflect the views of Loomis, Sayles & Company, L.P. Investment recommendations may be inconsistent with these opinions. There is no assurance that developments will transpire as forecasted and actual results will be different. Information, including that obtained from outside sources, is believed to be correct, but we cannot guarantee its accuracy. This information is subject to change at any time without notice.
Market conditions are extremely fluid and change frequently.
Any investment that has the possibility for profits also has the possibility of losses, including the loss of principal.
FOR INSTITUTIONAL USE ONLY. NOT FOR FURTHER DISTRIBUTION.
9099250.1.1
Authors